Blog

  • How to Sell a Mobile Home by Owner in San Diego

    How to Sell a Mobile Home by Owner in San Diego

    How to Sell a Mobile Home by Owner in San Diego

    To sell your mobile or manufactured home by owner in San Diego, first confirm whether you are selling a home in a mobile-home park on a rented space or a home with land. Review the home’s current title and registration, any outstanding loan or lien, and the park’s rental agreement and rules when applicable. Use recent sales of similar homes in the same park whenever possible to set an asking price, then prepare the home and organize the transaction documents.

    A homeowner can sell a used mobile home in a park without hiring the park manager as the sales agent. For a home that will remain in the park, park management may review the prospective buyer’s residency application, but that is separate from your right to sell the home. You must notify management of the sale before closing. For assistance with selling, visit SD Mobile Home Guide.

    Check San Diego Park Rules and Land Ownership

    Before setting a price or scheduling showings, confirm whether the sale includes the home only or both the home and the land.

    If the home is in a San Diego mobile-home park, review the rental agreement and written park rules. Ask management how it handles prospective residents, occupancy requirements, and any applicable sale-related paperwork. A park may screen the purchaser for residency, but it cannot require you to use park management as your sales agent.

    For a home that will remain in the park, the seller or seller’s agent must notify park management of the sale before closing. If management identifies any work it says is required as a condition of the sale, ask for the written explanation and its basis; California law limits park-required repairs and improvements.

    If the sale includes land, review the deed and relevant property records, and confirm whether the home is classified and recorded as real property rather than assuming it is.

    Price Your Mobile Home for the San Diego Market

    Start with recent sales of comparable homes in the same park, when available. Compare home age, size, layout, condition, repairs, upgrades, and included features.

    Do not assume a nearby park automatically provides comparable prices. A park’s location, upkeep, quality, amenities, buyer demand, and space rent can materially affect what buyers will pay, even when two parks are close together.

    For a home sold with land, use sales with a similar land-ownership arrangement rather than comparing it directly with a home on leased park space. If relevant sales are limited, a local mobile-home agent or qualified appraiser may help evaluate the differences.

    Prepare Your Home and Sale Documents
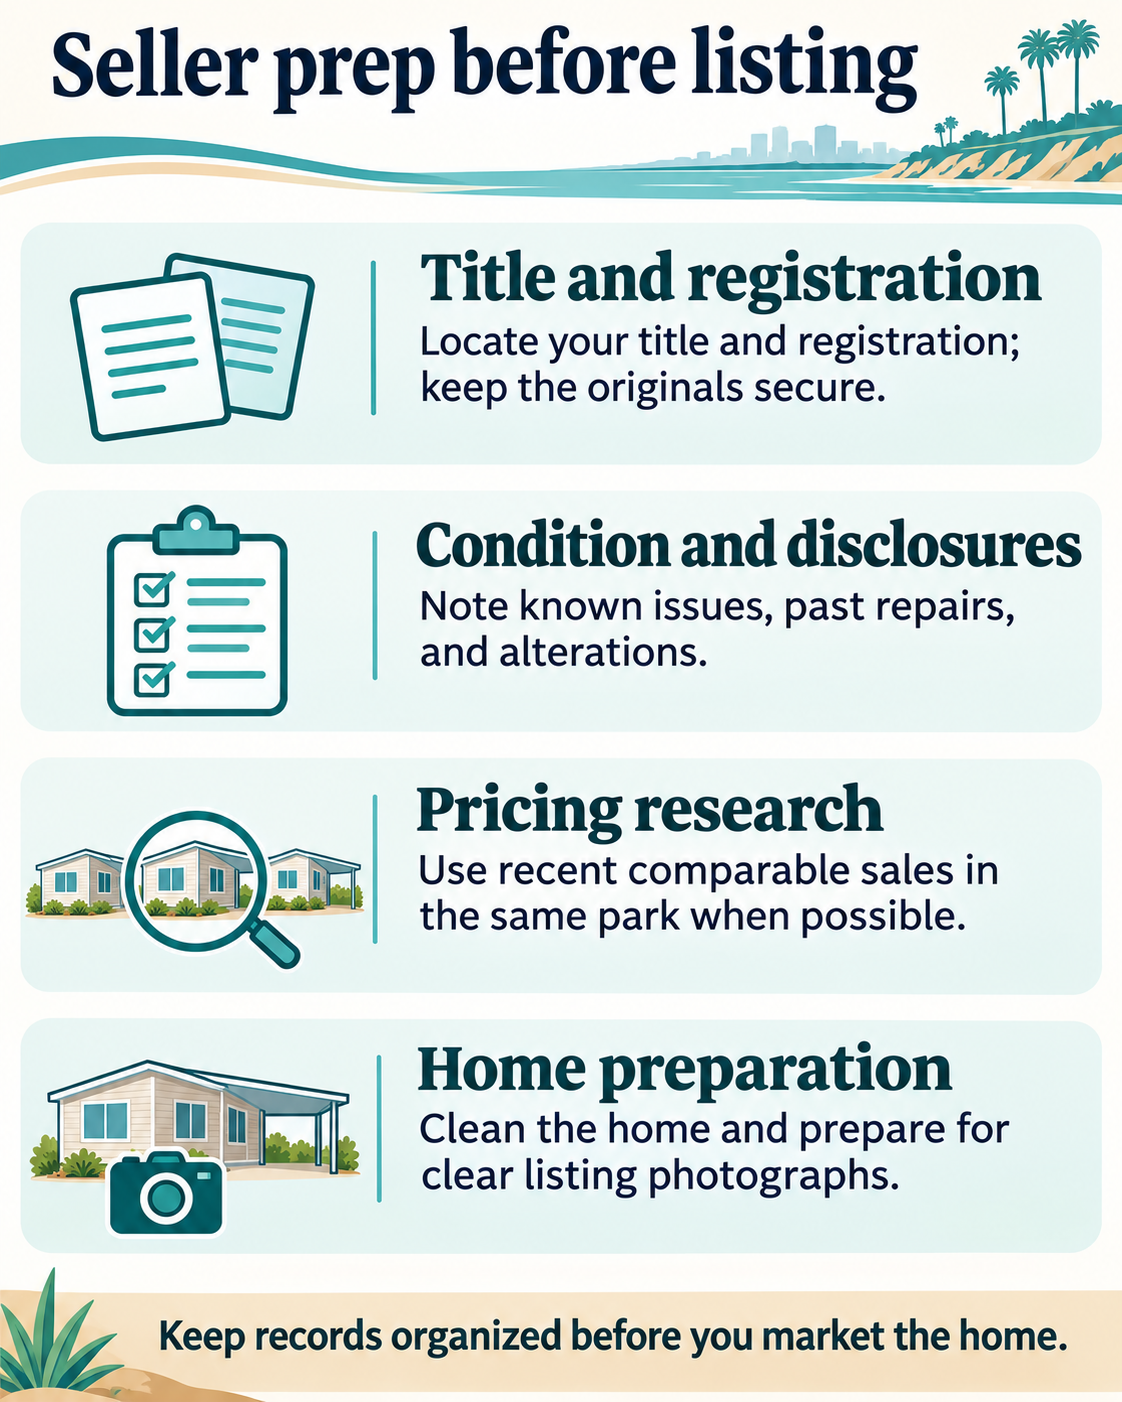
    Four unnumbered seller-preparation groups covering title and registration, condition and disclosures, pricing research, and home preparation.
    Organize records and condition notes, research pricing, and prepare the home for listing photographs.

    Clean the home, remove clutter, and address small repairs you decide to make before showings. Photograph the exterior, living areas, kitchen, bathrooms, bedrooms, and carport or patio if present.

    Locate the current Certificate of Title and registration card, verify the owner information, and check for a recorded legal owner or lienholder. If the title or registration is missing, or ownership information is inconsistent, contact the California Department of Housing and Community Development (HCD) for the appropriate replacement or transfer process.

    Keep original ownership documents secure while the transaction is being arranged. Make available information about known repairs, upgrades, and included appliances. For a park home, park-specific rent, rules, and residency details should be confirmed with management for the particular home and space when the transaction reaches that stage.

    Complete California Mobile Home Disclosures

    For a manufactured home or mobilehome sold in a mobilehome park, California’s resale disclosure requirements include the Manufactured Home and Mobilehome Transfer Disclosure Statement. Accurately disclose known defects, past damage, repairs, alterations, and other matters covered by the applicable form; selling as-is does not remove applicable disclosure duties.

    When a home will remain in the park, park management may request a copy of that disclosure statement in writing. If the sale includes land or involves a different legal ownership arrangement, confirm which additional or different disclosure requirements apply rather than assuming every property uses the same paperwork.

    Keep copies of completed disclosure documents and consult the current California forms or a qualified professional when a special circumstance is involved.

    Advertise the mobile home using clear photographs and an accurate description of its location, size, layout, condition, and included features. For a park home, identify the space-rent information you currently have, while making clear that the buyer should confirm the current, space-specific terms with park management.

    You may advertise a home that will remain in a park without appointing management to sell it. Follow reasonable rules for arranging access and showings, and do not promise that a prospective buyer has been accepted for residency.

    Ask prospective buyers about their purchase timeline and whether they understand that financing and park residency are separate processes. Protect personal information and arrange safe showings.

    Compare Offers and Set Sale Terms

    Evaluate offers for price, proposed financing, contingencies, closing timeline, and the buyer’s understanding of the park residency process if the home is in a park.

    Put the accepted terms in a written purchase agreement, including the price, deposit, included appliances or other items, contingencies, expected closing date, and how closing costs will be handled. An offer does not itself mean that park residency screening or lender review is complete.

    Keep copies of all signed agreements and coordinate any lien payoff or release as part of the transaction.

    Coordinate Park Residency and Transfer Ownership

    For an existing park home that will stay in the community, the prospective buyer completes any personal residency application and screening required by park management. Management’s review concerns whether the buyer may reside in the park; it is not the same as a separate approval of your right to sell the home.

    In the usual accepted-offer workflow, arrange for current space rent, written rules, and residency information for that specific home and space to come from park management. The law also provides ways for a prospective resident to request specified park information before an offer is accepted, so the accepted-offer timing is a transaction practice rather than a universal legal prerequisite.

    For an HCD title-and-registration transfer, use HCD’s private-sale instructions for the home’s existing ownership certificate and tax or registration category. The original title, most recent registration card, transfer forms, any lien release, and applicable tax documents are coordinated through the sale. A county tax-clearance certificate is required for certain locally taxed homes, not every mobile-home sale.

    Close the Sale and Hand Over the Home

    Before closing, confirm that required park notice has been given and that the residency and transaction conditions in the agreement have been addressed. Use the agreed escrow or other documented payment and closing arrangements, and follow the applicable HCD transfer instructions.

    Do not assume that every sale requires an identical notarization, payment method, or title-delivery process. Keep the original title and registration secure until the parties handling the closing are ready to complete the transfer. Hand over keys and possession according to the completed transaction and purchase agreement.

    Remove your belongings, document the final condition if appropriate, provide agreed keys and appliance information, and coordinate utility changes and any final park notifications.

    Conclusion

    Selling a mobile home by owner in San Diego involves more than advertising and accepting an offer. Start with accurate title and registration information, use the most relevant same-park comparables, provide applicable disclosures, and distinguish park residency screening from your right to sell.

    For a home staying in a park, notify management before closing, coordinate the required ownership transfer, and use the agreed closing process for payment and possession. For help selling a mobile or manufactured home in San Diego, visit SD Mobile Home Guide.
  • How to Sell a Mobile Home Without Owning the Land in San Diego

    How to Sell a Mobile Home Without Owning the Land in San Diego

    How to Sell a Mobile Home Without Owning the Land in San Diego

    You can sell an existing mobile or manufactured home in a San Diego mobile-home park even when you rent the space beneath it. You are selling your ownership interest in the home, not the park’s land. Start with the home’s current title and registration, check for outstanding liens, and review the park’s rules and prospective-resident application process. A sale of a home that remains in the park requires notice to management before closing, while the buyer’s residency review is separate from the seller’s right to sell. For help selling, visit SD Mobile Home Guide.
    Confirm You Own the Mobile Home

    Have the current Certificate of Title and registration card ready for review. If another owner or a lender is listed, work with your sales agent or the person handling the transfer to arrange any required signatures or lien release.

    If you cannot locate the title or registration card, contact the California Department of Housing and Community Development (HCD) for the applicable replacement instructions. Keep original ownership documents secure while arranging the sale; do not hand them to a prospective buyer simply to show that you own the home.

    Check San Diego Park and Lease Rules

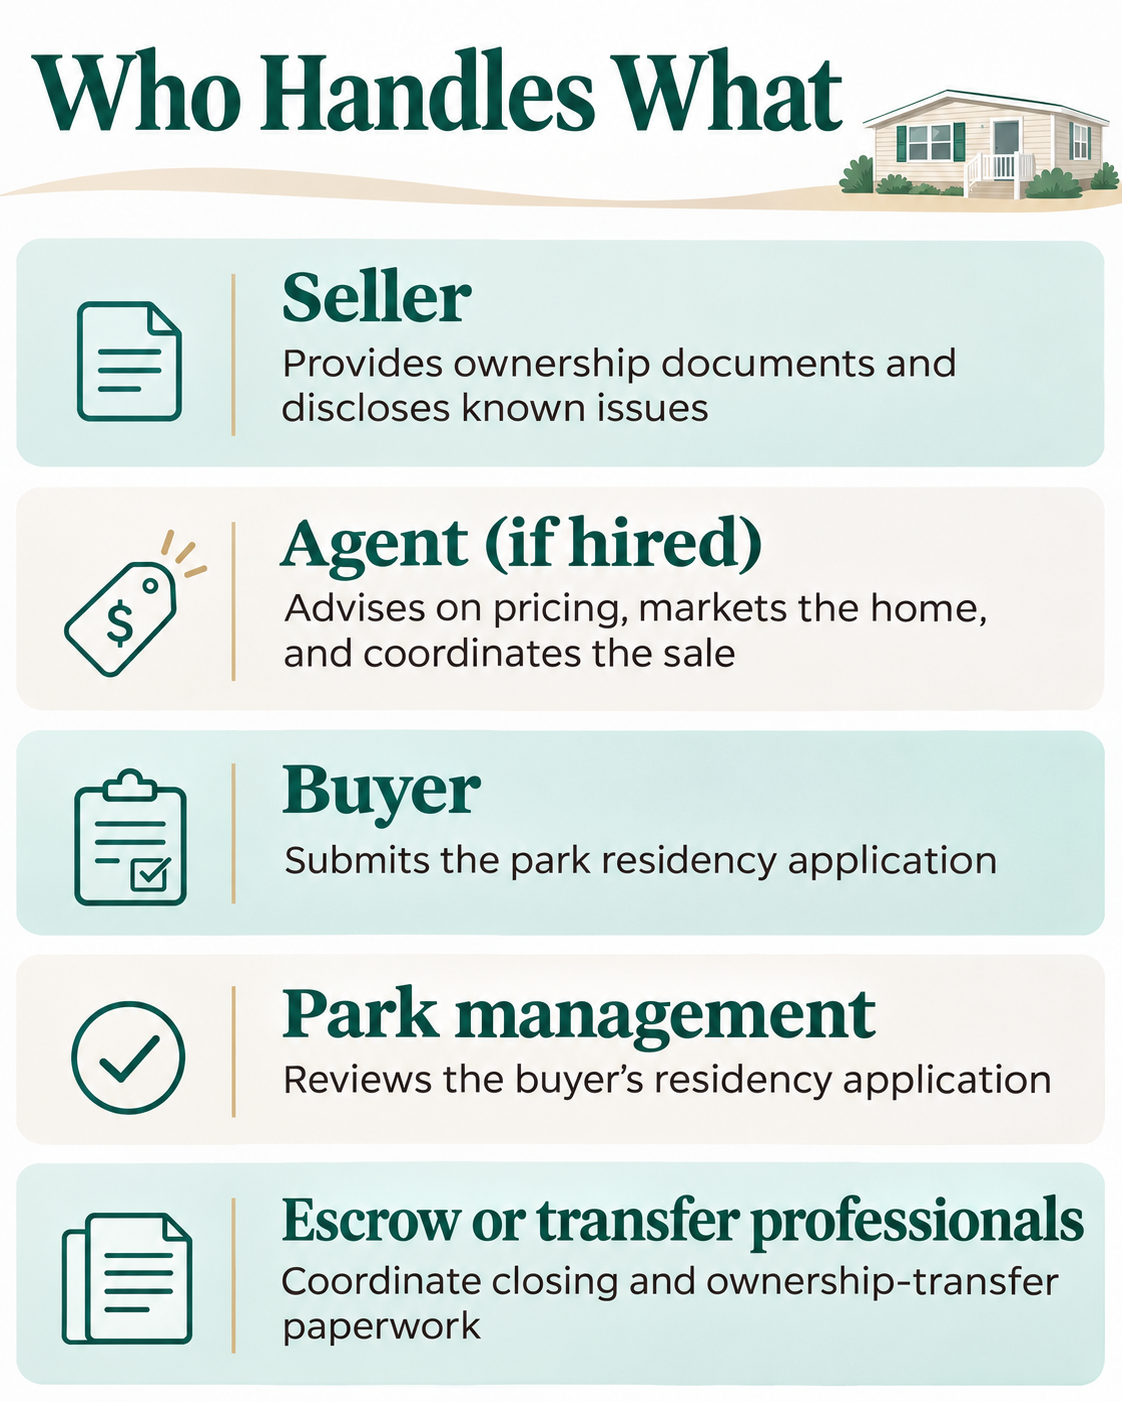
    Five unnumbered cards explaining seller, hired agent, buyer, park management, and escrow or transfer responsibilities.
    Different parties handle different responsibilities; agent services apply when an agent is hired.

    Read your park rental agreement and current written rules. Ask how management handles residency applications, occupancy requirements, and any sale-related information for a home that will remain on its space.

    California law allows management to review a prospective buyer for residency, but park management generally cannot prevent the homeowner from listing or selling the home or require the homeowner to use management as the selling agent. The seller or the seller’s agent must notify park management of a sale of a home that will remain in the park before closing.

    If you work with a sales agent, the agent can help confirm the current space rent, rental terms, rules, and residency requirements after you accept an offer. Buyers may have a legal right to request certain park information earlier; an accepted offer is not always required.

    Gather California Sale and Transfer Documents

    Start with the current title and registration card. The other transfer paperwork depends on the home’s ownership, liens, and tax or registration status. Follow HCD’s private-party sale instructions for the type of ownership certificate you have.

    Some homes still have a DMV-issued ownership certificate, often called a pink slip. Follow HCD’s instructions for that certificate; don’t assume the transfer should be handled at a DMV office.

    Depending on the home, the HCD transfer may also need a transfer form, lienholder release, or tax-related documents. A separate bill of sale is not required for every transaction. County tax clearance applies to certain locally taxed homes, not every park home.

    Complete the applicable Manufactured Home and Mobilehome Transfer Disclosure Statement and disclose known issues accurately. If the home stays in the park, management may request a copy of the statement in writing.

    Price and Prepare Your Mobile Home

    Start with recent sales of similar homes in the same park whenever possible. Compare home age, size, layout, condition, upgrades, needed repairs, and included features. The park’s location, condition, desirability, amenities, and space rent can affect the home’s value.

    Do not assume a sale from the closest park is necessarily a good comparable. Two parks near each other may have substantially different home values because of differences between the communities themselves.

    Clean the home, remove clutter, and discuss any repairs or an as-is sale with your sales agent if you have one. Make the home available for photographs and showings, and share accurate information about known issues, past repairs, and improvements.

    Find a Buyer and Coordinate Park Residency Review

    A sales agent can market your home with accurate details and a reasonable asking price, or you can handle the listing yourself if you’re selling without an agent. Park management cannot generally require you to use its listing service or selling agent. Confirm the practical arrangements for showings and inform serious buyers that buying the home and being accepted to reside in the park are different matters.

    The buyer, with help from the buyer’s agent if involved, submits the personal residency application and required signatures to management. Park management handles that screening process.

    Park management must follow California’s requirements when reviewing the buyer’s residency application. Do not promise a buyer guaranteed approval. This review determines whether the buyer can live in the park; it is separate from your right to sell the home.

    Transfer Title and Registration and Close the Sale

    Coordinate the title and registration transfer through the applicable HCD process and the parties handling closing. Resolve any recorded lien or legal-owner interest and follow the purchase agreement for funds, signatures, possession, and key delivery. The seller retains originals securely until the transfer is ready to be completed.

    A typical sale leaves the home on its current space. California limits when park management can require removal because a home is sold. A planned move calls for separate, transaction-specific advice.

    Keep copies of the completed agreement, disclosure paperwork, payment records, and transfer submissions. Coordinate utility account changes and the key handoff according to the agreed closing terms.

    Conclusion

    Before closing, review the remaining paperwork and deadlines with the person coordinating your sale. Know who is handling the title transfer, when payment and possession will change hands, and whether the buyer’s park application still needs attention.

    For help planning your sale, visit SD Mobile Home Guide.
  • How to Sell a Mobile Home in San Diego: A Step-by-Step Guide

    How to Sell a Mobile Home in San Diego: A Step-by-Step Guide

    How to Sell a Mobile Home in San Diego: A Step-by-Step Guide

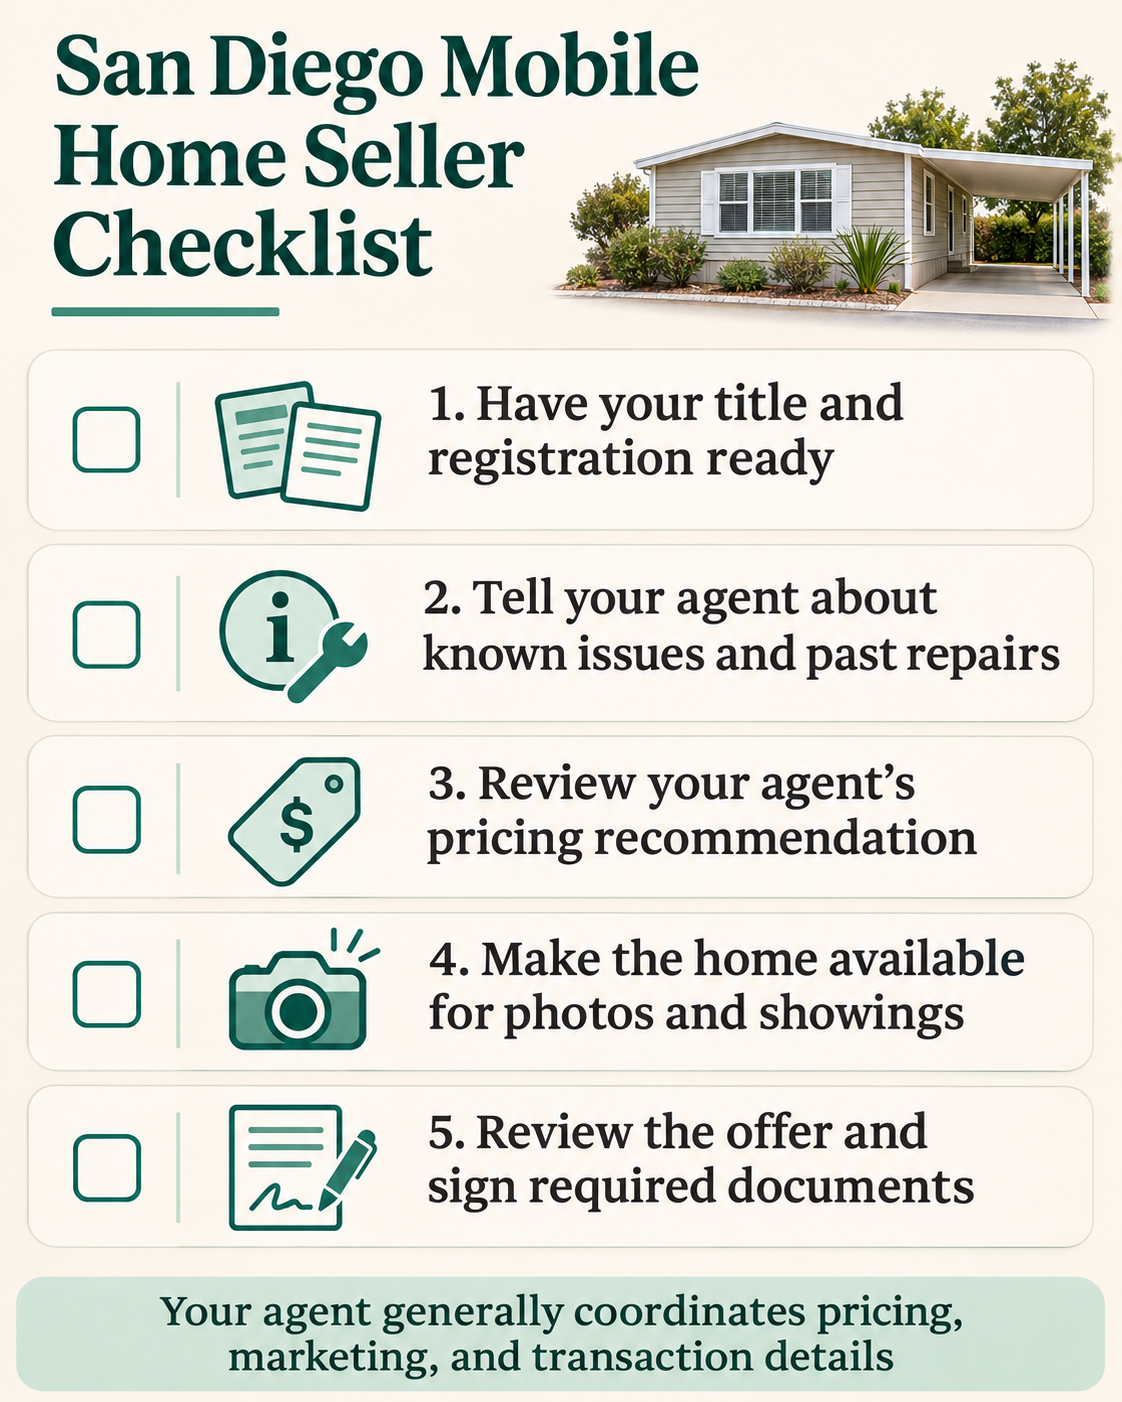
    Before listing an existing mobile home in a San Diego park, have your current title and registration ready for your mobile home sales agent. Share what you know about the home’s condition, including known problems, past repairs, and features that come with the home. The agent can review the ownership documents, advise on price, and coordinate the listing.

    Discuss whether to make repairs or sell as-is. Make the home available for photos and showings, review the offer with your agent, and provide the information and signatures needed for disclosures and closing. The agent works with escrow or transfer professionals to coordinate the paperwork.

    Have Your Title and Registration Ready

    Five seller actions covering title and registration, known issues and past repairs, agent pricing guidance, photos and showings, and offer review and signatures.
    Have documents ready, share accurate home information, review pricing guidance, allow photos and showings, and review the offer and sign required documents.

    For a home titled through California HCD, locate the current Certificate of Title and Registration Card and make them available to your mobile home sales agent.

    Your agent can review the title for registered owners and any listed lienholder, then help coordinate missing documents or lien releases. You may need to provide information or signatures. HCD requires a county tax-clearance certificate for a private sale of an HCD-titled home subject to local property tax.

    For a home titled and registered through HCD, use HCD’s ownership-transfer process. A home recorded as a real-property improvement under California’s foundation and recordation process transfers differently. Ask your agent to check the records if this might apply. Owning the land or having a foundation does not by itself establish real-property status.

    If you’re deciding whether to list, you can request a free Mobile Home Value Review by sharing your home’s details with our team. We’ll review your information and follow up to discuss its potential market value. This is not an appraisal or a guaranteed sale price.

    How Park Sale Requirements Are Coordinated

    For a mobile home that will stay in the park, California requires the seller or their agent to notify park management before the sale closes. Confirm with your agent who will give the notice. Management may separately require approval of the buyer for residency.

    Once both parties have accepted an offer, the buyer and their agent typically work with park management on space rent, park rules, the rental agreement, and the buyer’s residency application. The buyer can ask management for the park rules earlier.

    California limits the repairs or improvements a park can require as a condition of sale. If management raises a condition or exterior issue, ask your agent to review the written requirement.

    Review Your Agent’s Pricing Recommendation

    Your mobile home sales agent typically provides recent comparable sales and a suggested asking-price range. Review that information together; the most useful comparables are often recent sales of similar homes in the same park.

    The ownership arrangement matters: a home sold with land is not directly comparable to a home sold on a leased park space. Even among parks, location, park quality, and space rent can affect what buyers are willing to pay.

    Compare the home’s age, size, layout, condition, and included features with the homes that sold. If your agent uses sales from other parks, ask how their amenities and buyer demand compare. San Diego’s median house price is not a substitute for park-home comparables.

    Discuss the recommended asking price with your agent before deciding how to position the home. Overpricing may discourage buyers, while underpricing can reduce your proceeds.

    Discuss Repairs or Selling As-Is

    Tell your agent about known defects, past repairs, and anything that may need attention. Together, discuss whether modest repairs before listing make sense, such as fixing broken screens or damaged fixtures. Not every seller needs to renovate or repair the home before listing.

    If practical, clean and declutter the home and tidy the entry, carport, patio, and other areas that are actually present. Your agent can advise whether any additional presentation work would be worthwhile.

    You may decide to sell the home as-is. Repairs may not pay for themselves, and an as-is sale does not remove applicable seller disclosure obligations.

    Choose an Agent Who Knows Mobile Homes

    Consider working with a mobile home sales agent who has experience with existing homes in San Diego parks. These transactions can involve title and registration, park residency procedures, and other details that differ from a home sold with owned land.

    Ask how the agent handles title and registration review, provides same-park comparable sales and pricing guidance, arranges listing photos, and coordinates transaction documents and escrow.

    Before hiring an agent, ask about their mobile-home experience, how they’ll communicate with you, and how they plan to reach interested buyers.

    Your mobile home sales agent normally coordinates the listing, photography, and marketing. You do not need to independently create the listing or gather comparable sales.

    Make the home available for photographs and showings, and share accurate details about its size, layout, features, upgrades, condition, and known repair needs. The agent can arrange photos of the interior, exterior, carport, and other applicable features and prepare the listing from that information.

    Before the listing goes live, check that it accurately describes what comes with the home and that you understand the plan for showings.

    Review an Offer With Your Agent

    When an offer arrives, review the proposed price, financing terms, and timing with your agent. Consider whether those terms work for you before deciding.

    Loan options and lender requirements depend on the home, its title status, the transaction, and the buyer. Your agent can help explain any financing-related conditions in the offer, while the lender makes the financing decision.

    The agent can help provide documents about the home if the lender asks. The buyer handles their own financial information and loan requirements.

    Ask your agent to explain your estimated proceeds after applicable selling and transaction costs before accepting the offer.

    Share Disclosures and Sign Closing Documents

    Your agent and escrow or transfer professionals generally coordinate the closing paperwork, title transfer, and key handover. As the seller, be available to provide requested information, review documents, and sign where required.

    Provide any additional information or signatures needed for HCD transfer or tax documents. Your agent can help prepare the Manufactured Home and Mobilehome Transfer Disclosure Statement and other applicable forms, but you remain responsible for accurate disclosures and required signatures. If the home stays in the park and management requests the statement in writing, the homeowner must provide a copy.

    Before signing, ask which documents need an original signature or notarization and when they’re due.

    Once escrow or the transfer professional confirms the closing conditions and funds, arrange key delivery with your agent.

    Make the home available for an agreed final walk-through and set aside any manuals or warranties for items included in the sale.

    Conclusion

    Set aside your title and registration and jot down known problems and past repairs. Bring both to a conversation with a San Diego mobile home sales agent so you can decide what’s worth fixing before photos and when to list.

  • Can You Finance a Manufactured Home in a San Diego Mobile Home Park?

    Can You Finance a Manufactured Home in a San Diego Mobile Home Park?

    Can You Finance a Manufactured Home in a San Diego Mobile Home Park?

    Yes, you may be able to finance an existing manufactured home in a San Diego mobile home park even if you don’t own the land. A lender may offer a chattel loan, which uses the home as collateral rather than the land. Financing options and requirements vary by lender, home, transaction, and park.

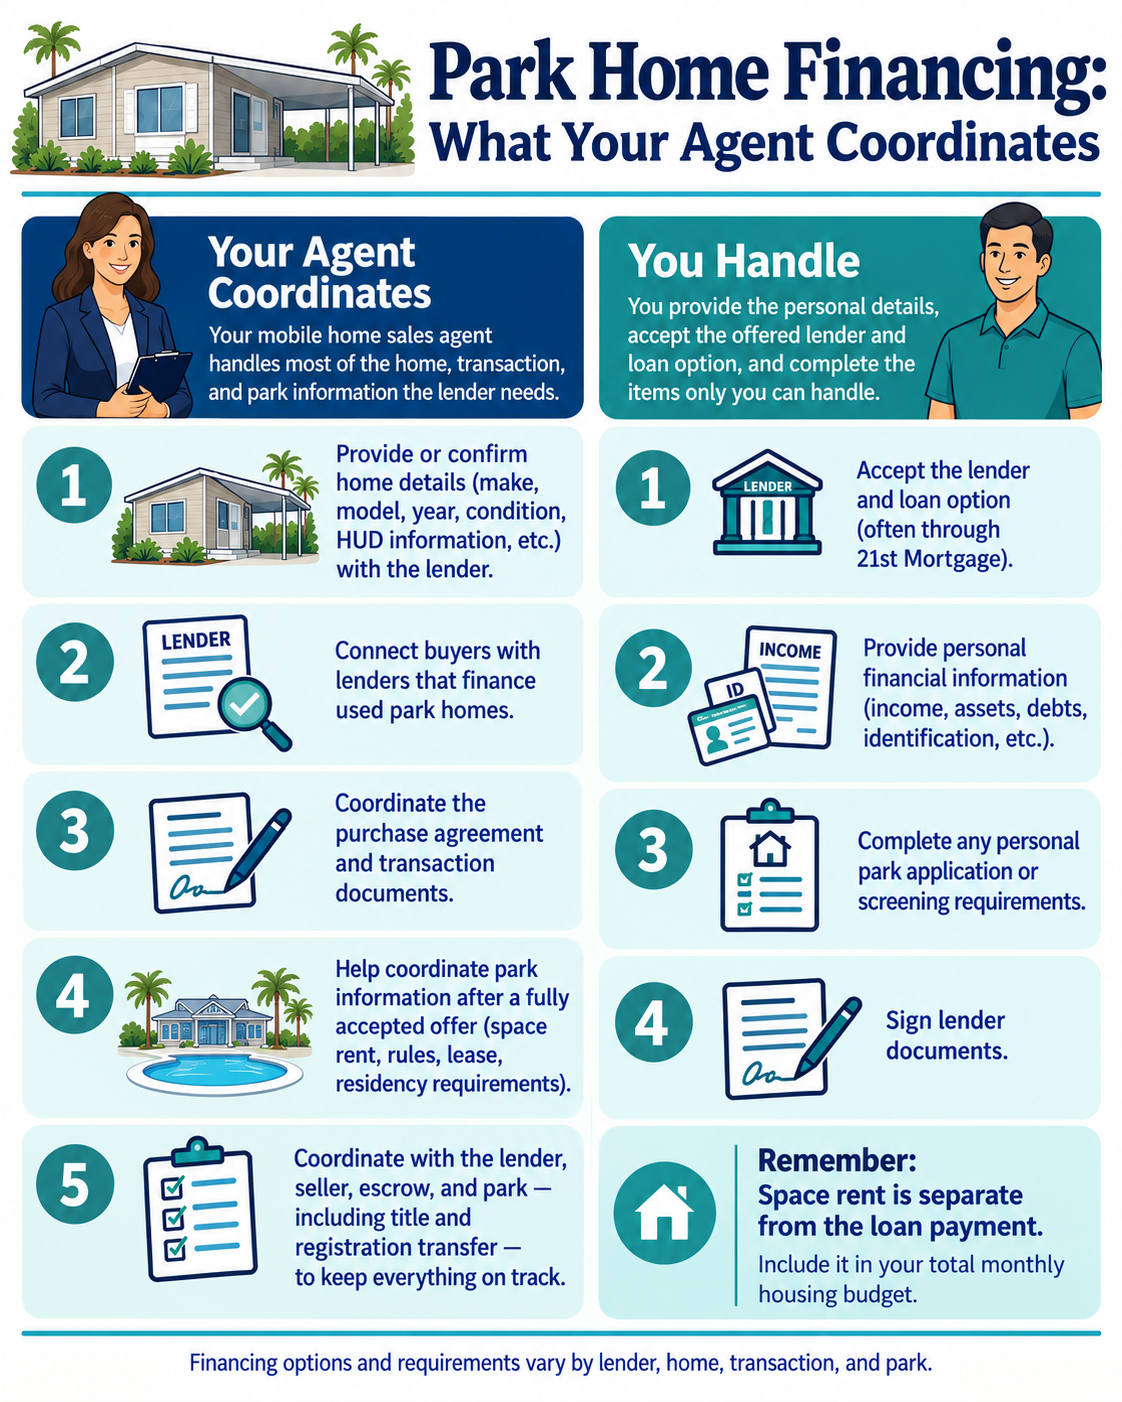
    When working with a mobile home sales agent, the agent can coordinate much of the financing-related process, including home information, connections with lenders that finance used park homes, purchase documents, and communication with the seller, escrow, and park management. The buyer generally reviews and accepts an offered lender and loan option, provides personal financial information, completes the park’s personal residency application or screening requirements, and signs lender documents. SD Mobile Home Guide is not a lender or underwriter. For help exploring homes for sale, visit SD Mobile Home Guide.
    Can You Finance a Home in a San Diego Park?

    You may be able to finance a manufactured home in a San Diego park, but financing can differ from a home sold with land. In a typical park transaction, you are buying an existing home already located in the community while leasing the space beneath it.

    A mobile home sales agent can help provide the home’s identifying information and condition details and connect buyers with lenders that finance used manufactured homes in parks. Financing is often arranged through 21st Mortgage in the agent-assisted workflow described here, although other lenders and options may be available depending on the transaction.

    The lender determines its financing requirements and reviews the buyer’s personal financial information. The buyer reviews the offered financing arrangement and decides whether to accept the lender and loan terms.

    After you have a fully accepted offer, the agent can help coordinate the current space rent, written rules, rental or lease information, and residency requirements with park management. The buyer completes any personal application, screening information, or signatures requested by the park.

    Which Loans Fit Manufactured Homes on Rented Lots?

    Park home financing workflow showing what a mobile home sales agent coordinates and what the buyer handles, including home details, lenders, transaction documents, park information, personal financial information, park applications, and lender signatures.
    A mobile home sales agent helps coordinate the home, lender, transaction, and park information. The buyer handles personal financial information, accepts the offered loan option, completes park application requirements, and signs lender documents.

    A chattel loan may finance a mobile home on a rented lot without using the land as collateral. This type of financing generally applies when the manufactured home is titled separately from the land.

    Loan options and terms depend on the lender, home, park, and transaction. Traditional real-property mortgages may not fit a home-only purchase because those loans commonly involve the home and land together.

    Some government-backed financing programs may be available when their requirements are met. A mobile home sales agent can help connect buyers with lenders that finance used park homes and coordinate the home-related information those lenders request.

    The buyer reviews the lender and loan option offered for the home, including the financing terms and required personal documentation.

    What Down Payment and Loan Terms Can You Expect?

    Down payment requirements, interest rates, repayment terms, and fees depend on the lender, home, park, and financing program.

    The lender will request the personal financial information needed to evaluate the buyer’s application. This may include income, assets, debts, identification, and available funds. The mobile home sales agent can coordinate the home and transaction information separately.

    Chattel loans can have different repayment periods and interest rates, so buyers should understand the full terms of the offered financing arrangement before accepting it.

    Review the down payment, monthly loan payment, interest rate, repayment term, fees, and any prepayment provisions.

    Space rent is separate from the home’s loan payment and should be included when evaluating the total monthly housing cost.

    To compare the home payment with space rent and other expected housing expenses, use the SD Mobile Home Guide affordability calculator as an educational budgeting tool. It does not determine lending decisions or loan terms.

    How Do Age and Condition Affect Financing?

    A mobile or manufactured home’s age and condition can affect the financing options available. Requirements vary by lender, financing program, home, and transaction. A lender may request an inspection, appraisal, or other documentation concerning the home.

    The mobile home sales agent can help provide or confirm the home’s make, model, year, serial number, condition, and available identifying information. HUD certification or data-plate information may also be requested when applicable.

    Some financing programs have requirements related to the home’s age, construction standards, condition, or valuation. The lender determines whether the specific home meets its requirements.

    Problems with the roof, plumbing, electrical system, structure, or other components may lead to additional documentation or repair requests. An appraisal or valuation may also affect the financing amount a lender is willing to offer.

    When the lender identifies a concern involving the home, the mobile home sales agent can help coordinate the requested information with the seller and other transaction participants.

    How Do Park Rules and Space Rent Affect Financing?

    Park residency and home financing are separate parts of the transaction. However, a lender may need information about the park’s rental or lease arrangement before completing the financing process.

    After a fully accepted offer, the mobile home sales agent can help coordinate the current space rent, written rules, rental or lease information, and residency requirements for the specific home and space with park management.

    The buyer completes the personal portions of the park’s residency application and screening process directly with management. In the agent-assisted workflow described here, this is generally handled before the buyer signs the final lender documents, although the timing of particular lender forms can vary.

    Space rent also affects the buyer’s monthly housing budget. The agent can help explain the current space rent separately from the loan payment so the buyer understands both expenses.

    Requirements vary by park, home, transaction, and lender. The agent helps coordinate the home and park information while the lender handles its financing review and park management handles the residency process.

    How Does Your Agent Coordinate Park Home Financing?

    In a transaction handled by a mobile home sales agent, the agent coordinates much of the home, transaction, and park information needed for financing. The buyer handles the personal information and required actions that only the buyer can complete.

    The agent generally begins by providing or confirming the home’s identifying information, including its make, model, year, serial number, condition, and available HUD information when applicable. The agent can then help connect the buyer with lenders that finance used park homes.

    The agent coordinates the purchase agreement and other transaction documents needed for the financing process.

    After a fully accepted offer, the agent can help coordinate access to the current space rent, written rules, rental or lease information, and residency requirements directly from park management.

    Throughout the transaction, the agent works with the lender, seller, escrow, and park management to help keep the necessary documents and information coordinated. This includes confirming that the seller’s title and registration are ready for transfer and helping coordinate those documents through escrow or the applicable transfer process. The buyer is not expected to take possession of the original title and registration during this process.

    The buyer’s responsibilities generally include reviewing and accepting the offered lender and loan option, supplying requested personal financial information, completing the personal park residency application or screening requirements, and signing the required lender documents.

    Although specific lender and transaction procedures can vary, this agent-assisted approach helps keep the home and transaction coordination separate from the buyer’s personal responsibilities.

    Conclusion

    You may be able to finance an existing mobile or manufactured home in a San Diego park even when the land is not included in the purchase. Available financing depends on the home, lender, transaction, and financing program.

    When working with a mobile home sales agent, the agent can help coordinate home details, lender connections, purchase and transaction documents, park information after a fully accepted offer, and communication with the seller, lender, escrow, and park. Title and registration are handled as part of the transaction and transfer process.

    The buyer generally reviews and accepts the offered financing arrangement, provides personal financial information, completes the personal park residency application or screening requirements, and signs lender documents.

    Remember that space rent is separate from the loan payment and should be included in the total monthly housing budget. SD Mobile Home Guide is not a lender or underwriter. To explore homes for sale, visit SD Mobile Home Guide.
  • How to Know If a Mobile Home Is Priced Right in San Diego

    How to Know If a Mobile Home Is Priced Right in San Diego

    How to Know If a Mobile Home Is Priced Right in San Diego

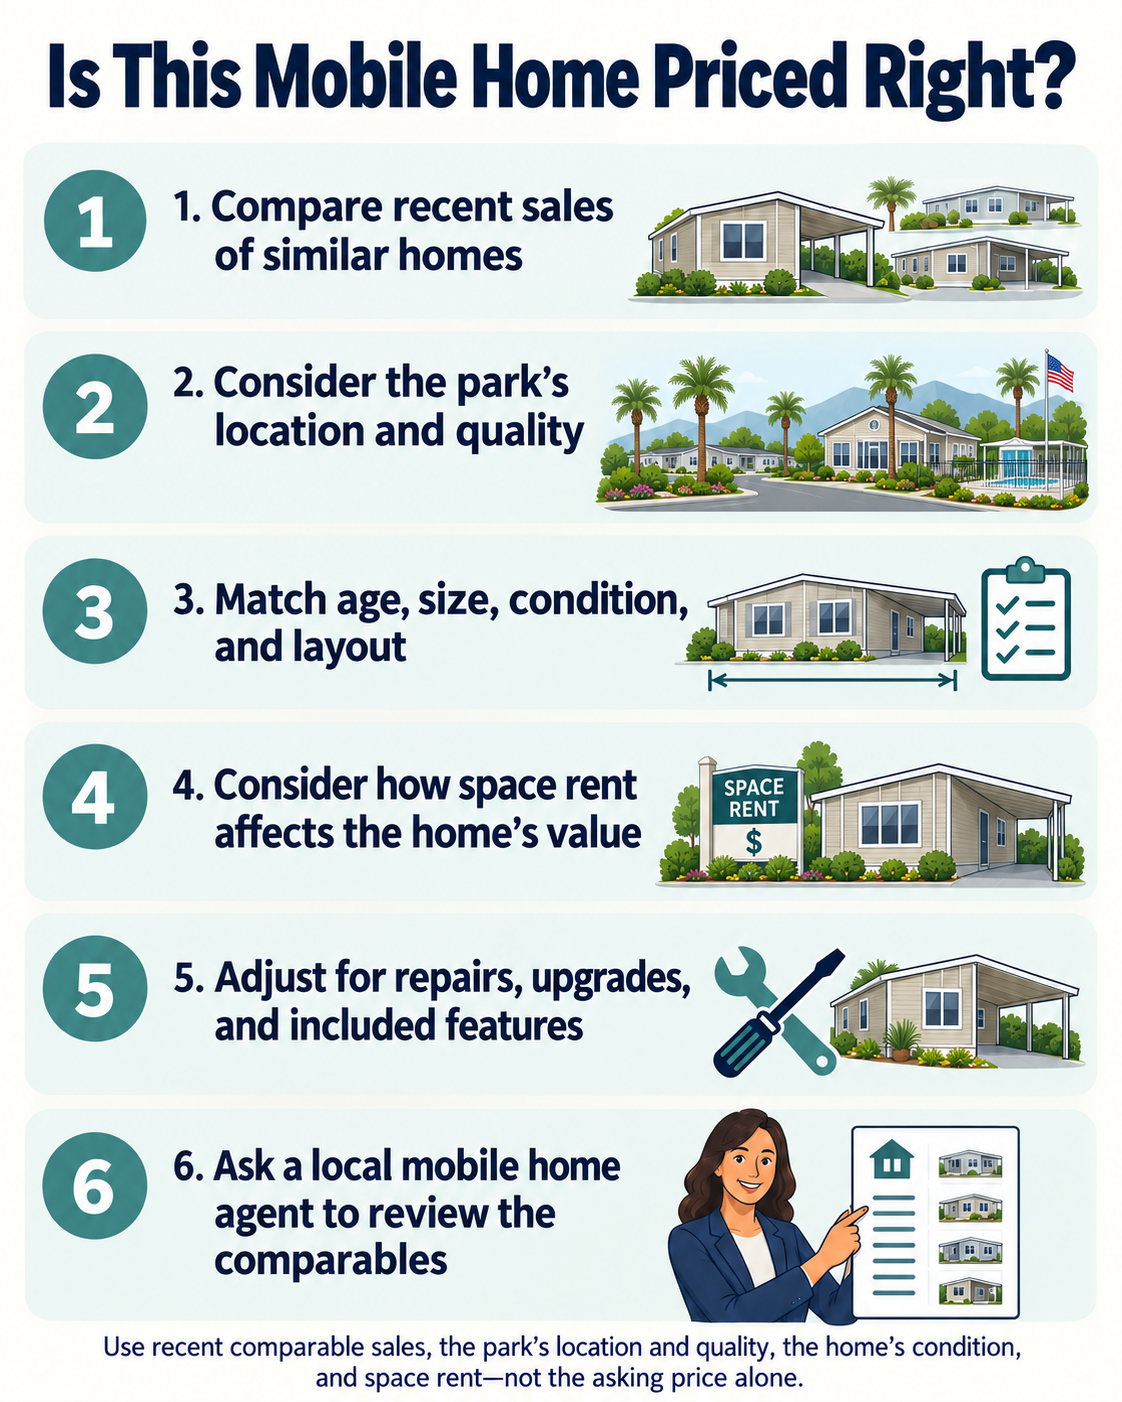
    Compare the mobile home with recent sales of similar homes in the same park whenever possible, matching for age, size, condition, layout, upgrades, and included features. Also consider the park itself, including its location, overall quality, amenities, and space rent, because those factors can affect what buyers are willing to pay. Account for needed repairs, then ask a local agent who works with mobile homes to review the comparables before you make an offer.

    Start With San Diego Mobile Home Comparables

    Start with recent sales of similar mobile homes in the same San Diego mobile-home park whenever useful comparables are available.

    Online real estate platforms can help you find listings and sale prices, but compare homes with similar age, size, condition, layout, upgrades, and included features rather than relying on price alone.

    Do not assume a home in a nearby park is automatically a good comparable. Two mobile-home parks only minutes apart can support very different home prices because of differences in location, overall park quality, amenities, buyer demand, and space rent.

    If you need to use sales from another park, compare the parks themselves as well as the homes. For a home in a mobile-home park, also consider how space rent affects the home’s value and your overall monthly housing cost. Once you have a fully accepted offer on a specific home, confirm the current space rent and what it includes directly with park management. You can also use the SD Mobile Home Guide affordability calculator as an educational budgeting tool when comparing the home price with your expected monthly housing costs.

    Compare Recent Sales of Similar Mobile Homes

    Mobile home pricing checklist covering recent comparable sales, park location and quality, home condition, space rent, repairs, upgrades, and local mobile home agent review.
    Use recent comparable sales, the park’s location and quality, the home’s condition, and space rent to help judge whether the asking price makes sense.

    Give the most weight to recent sales of similar mobile homes in the same park when judging whether an asking price is reasonable.

    Focus on sales that are recent enough to reflect current conditions, and compare the homes’ age, size, layout, condition, upgrades, and included features.

    If there are not enough useful sales in the same park, you may need to look at other communities. In that case, do not rely on distance alone. Compare the other park’s location, overall condition and appeal, amenities, space rent, and buyer demand.

    Two parks located a short distance from one another can support substantially different home prices if the parks themselves differ.

    Countywide housing statistics can provide broad market context, but they do not establish the value of a particular mobile home.

    Compare Age, Size, and Condition

    Within the most relevant comparable sales, compare mobile homes with similar age, size, layout, and condition.

    Age is one factor in a mobile home’s value, but it should be considered together with condition, size, updates, the park, space rent, and comparable sales.

    Check the square footage and layout, then consider the condition of the roof, plumbing, electrical systems, HVAC, appliances, and other major components.

    Recent improvements and good upkeep may help explain a higher asking price when comparable sales support it, while needed repairs may affect what you’re willing to pay.

    Give greater weight to similar homes in the same park before relying on homes from other communities.

    Consider the Park and Space Rent

    The mobile-home park itself can have a major effect on the value of a home. Consider the park’s location, overall appearance and condition, amenities, buyer demand, and space rent when comparing homes.

    Space rent can also affect what buyers are willing to pay for the home. Two otherwise similar mobile homes may support different sale prices when they are located in parks with different space rents or different levels of buyer demand.

    Use recent sales from the same park whenever possible. If you compare a home with sales from another park, make sure the communities themselves are reasonably comparable rather than assuming nearby parks have similar values.

    Once you have a fully accepted offer on a specific home, get the current space rent, what it includes, utility-billing information, written rules, and other applicable information directly from park management.

    Adjust for Repairs, Upgrades, and Included Features

    Check the mobile home’s systems, repairs, upgrades, and included features before deciding whether its asking price is reasonable. The condition of the plumbing, electrical system, HVAC, roof, and other major components can affect what you may need to spend after buying.

    Ask about their age and condition, inspect the home, and account for needed repairs.

    Upgrades such as newer appliances, updated flooring, improved windows, usable outdoor space, storage, or other desirable features may help explain a difference in price when comparable sales support it.

    Compare those differences with the most relevant recent sales rather than assuming the cost of an upgrade adds the same amount to the home’s value.

    Compare a mobile home’s asking price with recent sales and active listings for similar mobile homes before deciding whether it is reasonable.

    Countywide housing statistics are too broad to establish the value of a specific mobile home, especially when the park, space rent, home condition, and buyer demand can vary substantially from one community to another.

    Give the most weight to recent comparable sales in the same park. When same-park sales are limited, use homes from other parks only after considering differences in the parks’ location, quality, amenities, space rent, and overall desirability.

    Ask a Local Agent Before You Offer

    Ask a local mobile home agent to review recent sales and active listings for the park and home you’re considering. An agent familiar with San Diego mobile-home parks can help identify which sales are actually useful comparables.

    Ask how the home compares with recent sales in the same park and whether differences in age, size, layout, condition, upgrades, or included features help explain the asking price.

    If sales from another park are being used, ask whether that park is truly comparable in location, overall quality, space rent, amenities, and buyer demand rather than relying on geographic proximity alone.

    Conclusion

    To judge whether a mobile home is priced right in San Diego, start with recent sales of similar homes in the same park. Compare age, size, layout, condition, repairs, upgrades, and included features, then consider the park’s location, overall quality, amenities, and space rent.

    Do not assume a nearby mobile-home park is automatically comparable. Two communities only minutes apart can support very different home values. If the asking price is still difficult to judge, ask a local mobile home agent to review the most relevant comparable sales and explain the differences before you make an offer.

  • What to Expect After Your Offer Is Accepted on a Mobile Home in San Diego

    What to Expect After Your Offer Is Accepted on a Mobile Home in San Diego

    What to Expect After Your Offer Is Accepted on a Mobile Home in San Diego

    After your offer is accepted, track the escrow deadlines and complete each step needed to buy the mobile home. Send requested documents to your agent, escrow, and lender promptly. If the home is in a park, go to park management for the current space rent, written rules, utility information, and residency application and approval requirements for that home and space.

    Schedule an inspection with a qualified inspector familiar with manufactured homes. Review the inspection findings and address any repair or price negotiations under your purchase agreement. If your financing requires an appraisal, complete that step and continue working with your lender. As part of the financing process, review and accept the insurance quote required for the loan. Before closing, review the final escrow and lender documents and complete a final walk-through of the home.

    Start With Your Accepted Mobile Home Offer

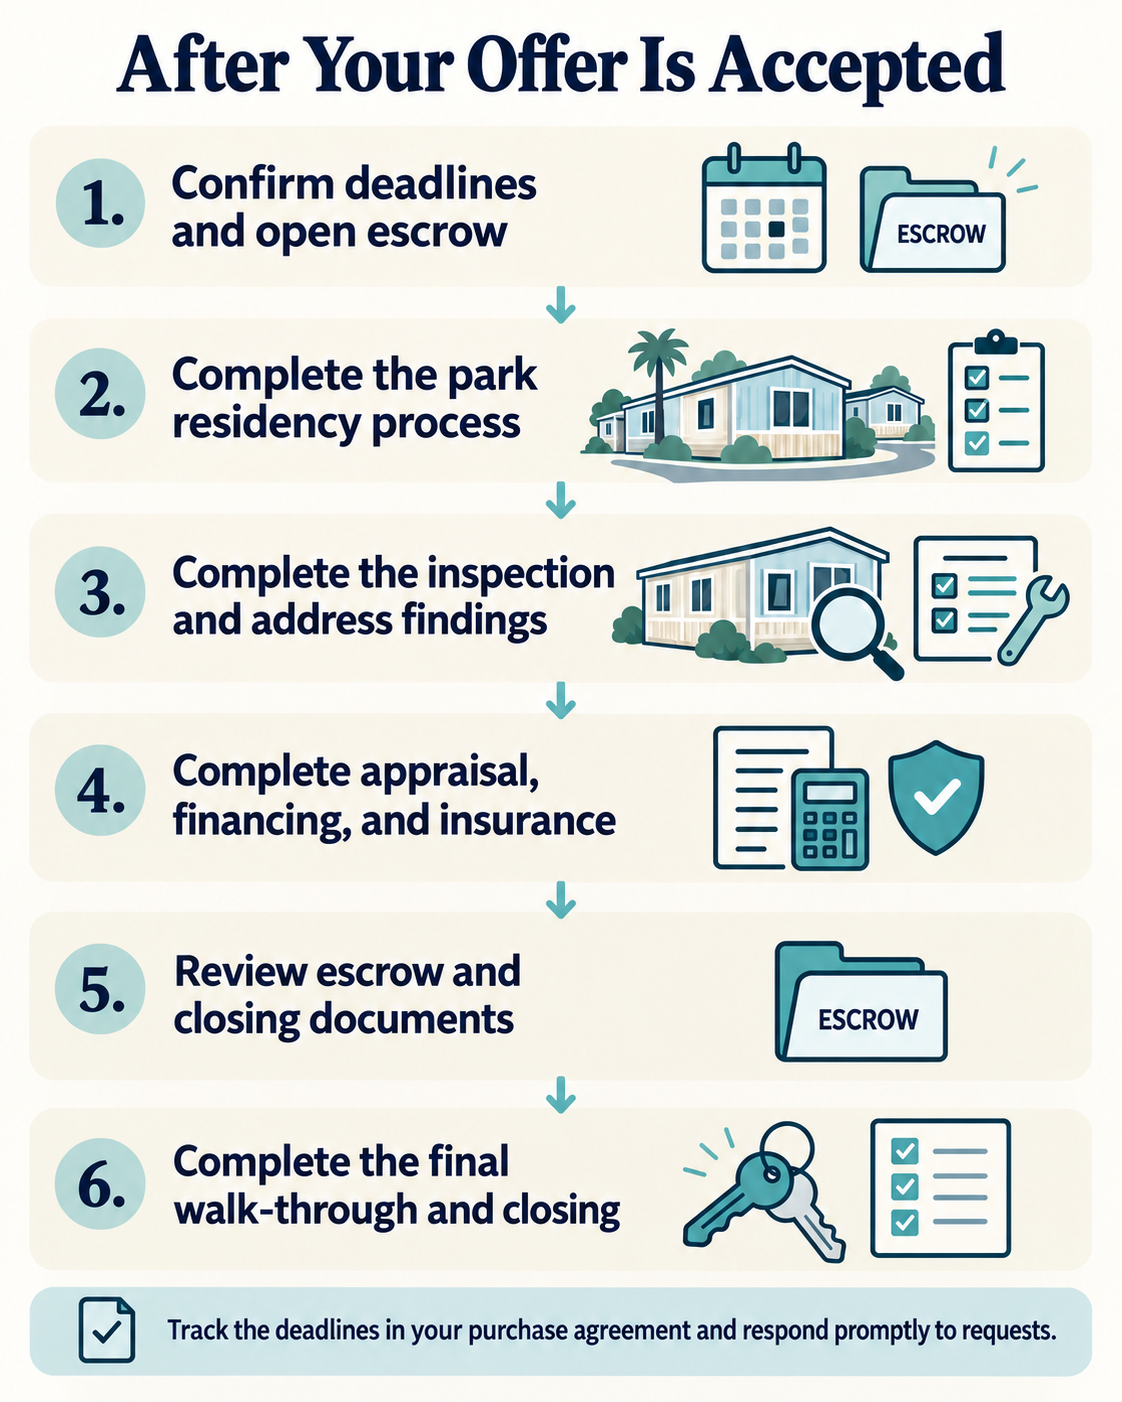
    Post-offer mobile home workflow covering escrow deadlines, park approval, inspection, financing and insurance, closing documents, and final walk-through.
    After acceptance, track escrow deadlines, park approval, inspection findings, financing and insurance, closing documents, and the final walk-through.

    After the seller accepts your offer, begin the park approval process and confirm your financing, inspection, and closing requirements.

    Park applications may request financial information, identification, a background check, age-related information for an age-restricted community, or other information used in the park’s screening process. Ask the park manager for the specific requirements that apply to the community.

    Arrange an inspection of the mobile home with an inspector familiar with manufactured-home construction. The inspector can check the structure, support system, plumbing, electrical system, and other accessible components.

    Review your purchase agreement’s contingencies and deadlines so you understand what must happen for the sale to proceed and what options the agreement gives you if an issue arises.

    Gather the income, asset, credit, and other documents your lender requests, and continue the financing process.

    Before closing, review the expected loan, escrow, insurance, and other transaction costs that apply. For a park home, also confirm the current space rent, separately billed utilities, and other recurring park charges with park management. You can use the SD Mobile Home Guide affordability calculator as an educational budgeting tool to see how those housing costs may fit your budget.

    Confirm Deadlines and Open Escrow

    Check your purchase agreement for deadlines to open escrow and complete inspections, appraisals, financing, park approval, and other contingencies that apply to your transaction.

    These dates determine when you must act and can affect whether the sale proceeds under the agreed terms.

    Escrow holds funds and documents while the transaction’s conditions are completed.

    Confirm the deadlines with your agent and escrow officer, and ask them to explain anything unclear.

    Send requested documents, such as proof of funds and required disclosures, promptly, and contact the appropriate transaction professional if an issue could affect a deadline.

    Get Park Residency Approval in Writing

    If the home is in a mobile-home park, complete the park’s residency application and approval process before completing the purchase. Follow your purchase agreement for the timing of any park-approval contingency or other contingency decisions.

    Park management may request information about your financial ability to pay the park rent and charges, identification, a background check, prior tenancy information, age-related information for an age-restricted community, or other information permitted as part of its screening process. Ask management for the current written requirements rather than relying on a general income multiple or another park’s standards.

    Request written confirmation of the park’s decision and keep it with your transaction records.

    If anything about the approval is unclear, ask the park manager and your agent or transaction professional before you proceed.

    Schedule a Mobile Home Inspection and Address the Findings

    Schedule an inspection after the seller accepts your offer and within the inspection period in your purchase agreement. A qualified inspector can assess the mobile home’s condition before closing and identify issues that may need further evaluation or repair.

    Choose an inspector familiar with manufactured-home construction and ask them to examine the support system, marriage line when applicable, plumbing, electrical system, roof, and other accessible components.

    When you receive the report, review the findings with the inspector and ask which concerns are urgent, which may need a specialist, and which can be planned for later.

    If the report identifies needed repairs, use the documented findings to discuss repairs, a price adjustment, or other terms with the seller, subject to your purchase agreement. Put any agreed changes in writing.

    Any repairs the seller agrees to complete can be checked again during the final walk-through before closing.

    Review the Mobile Home Appraisal

    If your lender requires an appraisal, the appraisal estimates the home’s value for the financing decision. The appraiser may consider comparable manufactured-home sales, the home’s age and condition, and other characteristics relevant to the appraisal.

    Review the appraisal report for the estimated value and any conditions or concerns noted for the loan. If the appraised value is below the purchase price, ask your lender and agent about the options available under your financing and purchase agreement.

    Keep the appraisal separate from the home inspection: an appraisal is primarily a valuation for the lender, while the inspection is intended to evaluate the home’s condition in more detail.

    Complete Financing and Insurance

    After your offer is accepted, continue the financing process for the type of manufactured home and site arrangement you are buying.

    For an existing home in a mobile-home park, ask the lender whether it finances used manufactured homes on rented or leased spaces and what home, park, or site documents it needs. Home-only or personal-property financing may be available for some park homes.

    If the manufactured home is sold with owned land, mortgage financing may be available when the property and borrower meet the lender’s and loan program’s requirements. Some government-backed manufactured-home programs can also apply to homes on leased lots, so do not assume land ownership by itself determines the available loan type.

    Provide the income, asset, credit, and property information the lender requests. Park residency approval is a separate process from lender underwriting, although the lender may request park or site documents for the loan.

    As part of the financing process, you will receive an insurance quote to review and accept. The required insurance coverage needs to be in place for the lender to complete the financing, so respond promptly to any insurance documents or requests connected with the loan.

    Review Escrow and Closing Documents

    As the transaction moves toward closing, escrow coordinates the ownership-transfer paperwork, including the title and registration transfer, and lets you know which documents or signatures are required from you.

    You do not need to independently clear the title or manage the seller’s title and registration. Respond to requests from escrow and ask the escrow officer or your agent about anything you do not understand.

    Review the final lender and escrow documents, including the charges and terms that apply to your transaction, before signing.

    Complete the Walk-Through and Close

    Before closing, walk through the mobile home and confirm it is in the agreed condition. If the seller agreed to complete repairs after the inspection, check that those items have been addressed.

    Check the status of the purchase agreement’s contingencies, including park approval, inspection, and financing when applicable.

    Review the final lender and escrow documents and ask about any charge or term you do not understand before signing. If your loan uses a Closing Disclosure, review that document as part of the process.

    Make sure the required insurance coverage is in place and that you know the amount and method required for any funds due at closing.

    Sign the documents required to complete the purchase. Escrow handles the title and registration transfer as part of the closing process. Possession and delivery of the keys should follow the timing stated in your purchase agreement and closing instructions.

    Conclusion

    After your offer is accepted, track each deadline and respond promptly to requests. Get the current park information and complete the residency-approval process, arrange the mobile home inspection, address any inspection-related negotiations, and complete the appraisal, financing, and required insurance steps.

    Escrow handles the title and registration transfer as part of closing. Review the final lender and escrow documents, complete the walk-through, confirm any agreed repairs have been addressed, and follow the closing and possession instructions for the transaction.

  • What Buyers Should Know About Property Taxes on Manufactured Homes in California

    What Buyers Should Know About Property Taxes on Manufactured Homes in California

    What Buyers Should Know About Property Taxes on Manufactured Homes in California

    In California, a manufactured home may be subject to annual local property tax or an annual vehicle license fee, also called an in-lieu fee. The tax system depends mainly on when the home was first sold new and whether it was later converted to local property taxation. A home can still have an HCD title and registration while being subject to local property tax, so HCD registration by itself does not tell you which tax system applies.

    Before buying, start with the current title and registration, then confirm the home’s tax status with the California Department of Housing and Community Development (HCD) or the county assessor as appropriate. If the home is in a mobile-home park, space rent is separate from the home’s property tax or in-lieu fee.

    Will Your California Manufactured Home Pay Property Tax or an In-Lieu Fee?

    Comparison of local property taxation and the HCD in-lieu fee system for California manufactured homes.
    Confirm whether the specific home is on local property taxation or the HCD in-lieu fee system before estimating ongoing ownership costs.

    A manufactured home first sold new on or after July 1, 1980 is generally subject to local property taxation. A home first sold new before that date may still be under the annual HCD vehicle license fee, or in-lieu fee, system if it was not later converted to local property taxation.

    Owners of certain older homes can voluntarily convert from the in-lieu fee system to local property taxation. Once a home is converted to local property taxation, it cannot be converted back to the in-lieu fee system.

    Do not assume that an HCD title or registration card means the home is on the in-lieu fee system. HCD has transfer procedures for both locally taxed homes and homes on yearly registration renewal.

    Use the current title and registration as your starting point, and confirm the tax status with HCD or the county assessor if it is unclear.

    How Does Owning the Land Affect Your Tax Bill?

    If you own the land beneath an HCD-titled manufactured home that is subject to local property taxation, the county generally assesses the land separately from the home.

    A manufactured home that has been installed on an approved permanent foundation and completed the process to become real property is treated differently. In that situation, the home is taxed as real property with the land rather than under the manufactured-home property-tax rules that apply to an HCD-titled home.

    Your property-tax bill can also include taxable improvements and voter-approved assessments or other charges that apply to the property.

    Review the home’s title and registration and the county property records so you understand how the home and land are currently treated.

    What Do California Mobilehome Park Residents Pay?

    If you buy an existing mobile home in a California park and rent the space beneath it, the space rent is separate from the home’s tax obligation.

    The home itself may be subject to local property tax or, for certain older homes, the HCD in-lieu fee system. A locally taxed manufactured home can remain personal property even though the county assesses it under the Manufactured Home Property Tax Law.

    For a locally taxed manufactured home on rented or leased land, the county assessor does not include value attributable to the particular rented site when valuing the home.

    After you have a fully accepted offer on a specific park home, get the current space rent, utility-billing information, and other recurring park charges directly from park management so you can budget those costs separately from taxes.

    How Does California Assess a Manufactured Home’s Taxable Value?

    For a manufactured home subject to local property taxation, a change in ownership generally establishes a new base-year value based on the home’s full cash value at that time.

    In later years, the assessor generally enrolls the lower of the adjusted base-year value or the home’s current full cash value. The inflation adjustment to the base-year value is limited to no more than 2% per year under California’s Proposition 13 rules.

    If the home’s market value falls below its adjusted base-year value, contact the county assessor about a possible temporary reduction in assessed value.

    The home’s age, condition, features, and market evidence can affect its assessed value. For a home on rented or leased land, the assessor does not include site value attributable to the rented space.

    Who Collects California Manufactured Home Taxes?

    For a manufactured home subject to local property taxation, the county assessor determines the taxable value and the county tax collector bills and collects the property tax.

    For a home that remains under the HCD vehicle license fee, or in-lieu fee, system, HCD handles the yearly registration renewal and applicable in-lieu fee.

    Because both locally taxed homes and yearly-renewal homes can have HCD title records, check the home’s current documents and contact HCD or the county assessor if the tax status is not clear.

    When Are Manufactured Home Taxes Due in California?

    For a manufactured home subject to local property taxation, the annual tax is generally payable in two installments. The first installment is due November 1 and becomes delinquent after December 10. The second is due February 1 and becomes delinquent after April 10.

    A purchase or other change in ownership of a locally taxed manufactured home can also result in a supplemental assessment. Supplemental bills have their own due and delinquency dates based on when the bill is issued.

    If the home is under the HCD in-lieu fee system, follow the renewal and payment information provided by HCD.

    Check the actual county tax bill or HCD renewal notice for the dates and payment instructions that apply to the home.

    How Can You Estimate Taxes Before Buying a Manufactured Home?

    Before buying, review the current title and registration and determine whether the home is on local property taxation or the HCD in-lieu fee system. If the status is unclear, confirm it with HCD or the county assessor.

    If local property tax applies, ask the county assessor how the home is currently assessed and how a change in ownership may affect the assessed value. The final tax bill can also include voter-approved assessments or other charges that vary by location.

    If the home remains under the HCD in-lieu fee system, review the current renewal information and ask HCD about the fee that applies to the home.

    For a locally taxed manufactured home, also allow for the possibility of a supplemental assessment after the purchase. If you are comparing the home price, taxes, space rent, and other monthly housing costs, use the SD Mobile Home Guide affordability calculator as an educational budgeting tool rather than a tax estimate or financing-approval tool.

    Conclusion

    Before buying a manufactured home in California, determine whether the home is subject to local property tax or the HCD in-lieu fee system. Start with the current title and registration, then confirm anything unclear with HCD or the county assessor.

    If the home is in a mobile-home park, keep the home’s tax obligation separate from space rent, utilities, and other park charges. If you are buying a home with land, also review how the land and home are classified and assessed. Understanding the home’s current tax status before closing will give you a more accurate picture of your ongoing ownership costs.

  • What Park Rules Should You Review Before Buying a Mobile Home in San Diego?

    What Park Rules Should You Review Before Buying a Mobile Home in San Diego?

    What Park Rules Should You Review Before Buying a Mobile Home in San Diego?

    Once you have a fully accepted offer on a specific mobile home, get the park’s current written rules from park management before completing the purchase. Review age and occupancy requirements, guest rules, pet policies, parking, storage, shared-area rules, and any requirements that apply to the outside of the home or space.

    Ask the park manager for the current space rent, what it includes, other recurring charges, utility-billing information, and the residency-approval requirements. Also review rules for exterior changes, landscaping, maintenance, noise, and community conduct. These details can affect your costs and day-to-day life, so use the current information for the specific home and space.

    Get San Diego Park Rules in Writing

    Mobile home park rules checklist covering residency, pets and guests, rent and fees, home changes, parking, and approval.
    Review the current written park rules, charges, and residency requirements that apply to the specific home and space.

    After you have a fully accepted offer, get a current written copy of the park rules directly from park management before completing the purchase.

    Review policies on pets, landscaping, exterior changes, maintenance, parking, guests, and other rules that affect how you plan to use the home and space.

    Ask management to explain any rule you do not understand and keep a copy of the current documents for reference.

    Check Age and Residency Rules

    Review the park’s written age, occupancy, and guest rules as part of the park information you receive during the transaction.

    Some communities are age-restricted, while others have different occupancy requirements. Ask park management who may reside in the home and what rules apply to additional occupants and guests.

    Check how long guests may stay and any registration or notice requirements that apply.

    These rules can affect whether the community fits your household and visiting family.

    Review Space Rent, Fees, and Increases

    Once you have a fully accepted offer, ask the park manager for the current space rent, what it includes, and any other recurring charges that apply to the specific home and space.

    Review how utilities and services are billed, when rent is due, and any written terms or notices that describe rent changes and other charges.

    Use the current park information rather than relying on an older listing, advertisement, or general estimate.

    These details will help you estimate the monthly housing cost. You can also use the SD Mobile Home Guide affordability calculator as an educational budgeting tool when comparing the home price, space rent, utilities, and other recurring costs.

    Check Pet and Visitor Policies

    Ask the park manager for the current pet and visitor rules that apply to residents.

    Pet policies may address the number or type of animals, registration, designated areas, noise, or other conduct requirements. Include any applicable recurring or one-time charges in your budget.

    Review visitor and guest rules, including any registration or length-of-stay requirements, so you know how they may affect family and friends who visit.

    Review Home Changes and Maintenance Rules

    Review the park’s rules for exterior changes and maintenance. Depending on the park, management approval may be required for changes such as a porch, deck, awning, exterior paint color, or changes to the outside area around the home.

    Ask which exterior or site changes require written park approval before work begins. Government permits or inspections may separately apply to some projects, but do not assume every interior or exterior change follows the same process.

    Confirm the resident’s responsibilities for exterior upkeep, landscaping, and the area around the space, along with any timeframes for required maintenance.

    Ask how the park handles rule or maintenance issues if required work is not completed.

    Check Parking, Storage, and Shared Areas

    Check how many vehicles each home may park, whether visitor spaces are available, and where guests can leave their cars.

    Ask where residents may store an RV, boat, or other personal items and whether designated storage areas are available.

    Review the rules for shared spaces such as pools and clubhouses, including hours, reservations, guest access, and any resident responsibilities that apply.

    Review Noise and Neighbor Rules

    Check the park’s quiet hours and rules for music, repairs, vehicles, and other activities that may create noise.

    Review how the park handles complaints and rule enforcement rather than assuming every community follows the same process.

    If a dispute arises, follow the park’s written procedures and contact management when appropriate.

    Complete Park Approval Before You Complete the Purchase

    Park residency approval is separate from buying the mobile home. Once you have a fully accepted offer, go to the park manager for the current residency application and approval requirements.

    Depending on the park, the application may request financial information, identification, a background check, age-related information for an age-restricted community, or other information used in its screening process.

    Also confirm the current space rent, recurring charges, pet rules, and other requirements that apply to your household.

    Complete the park’s required approval process before completing the home purchase.

    Conclusion

    After you have a fully accepted offer on a mobile home in a San Diego park, get the current rules, space-rent information, utility details, and residency-approval requirements directly from park management. Review the rules that affect your household, vehicles, pets, guests, exterior changes, maintenance, and use of shared areas.

    Use the current park documents for the specific home and space, ask management to explain anything that is unclear, and complete the required residency-approval process before completing the purchase.

  • Should You Buy a Mobile Home in a Park or With Land in San Diego?

    Should You Buy a Mobile Home in a Park or With Land in San Diego?

    Should You Buy a Mobile Home in a Park or With Land in San Diego?

    Buying a mobile home with land gives you ownership of both the home and the property, while a park home usually means buying an existing home in the community and paying rent for the space beneath it. That difference affects your ongoing costs, control over the property, and financing options.

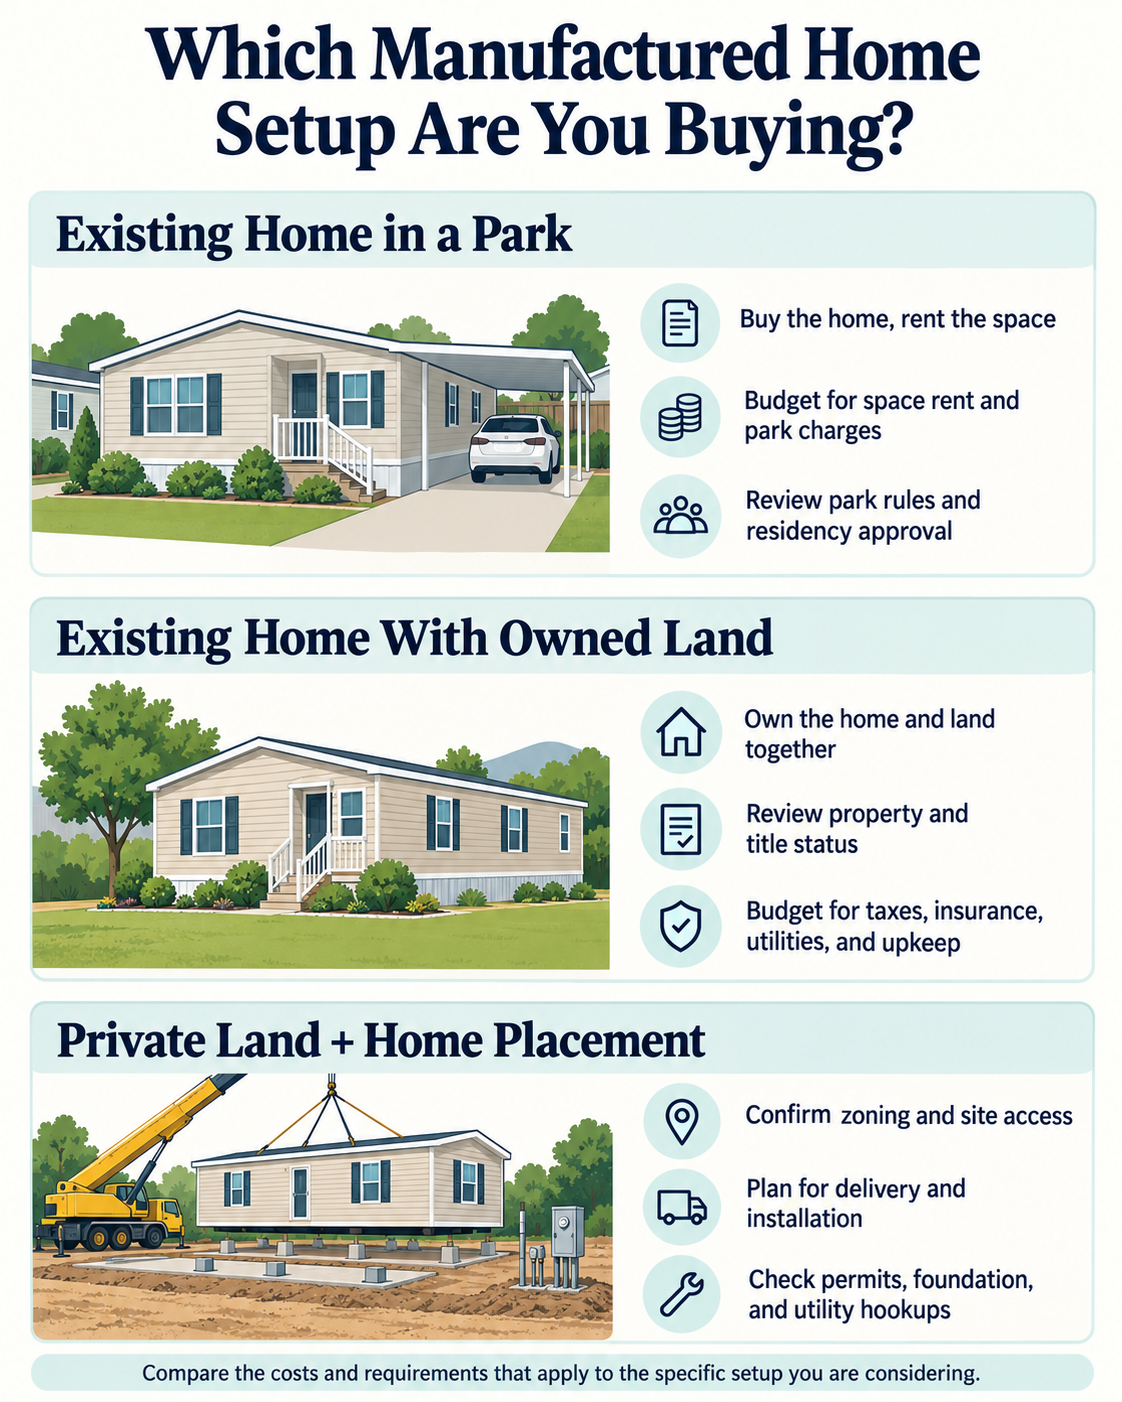
    If you are buying an existing manufactured home with owned land, review the property and title status, utilities, and ongoing costs. If you are buying private land to place a manufactured home, also check zoning, delivery access, installation requirements, permits, and utility hookups. For a park home, compare the expected space rent and park costs when deciding which option fits your budget; once you have a fully accepted offer on a specific home, get the current rent, written rules, and residency-approval information directly from park management.

    Should You Buy a Mobile Home in a Park or on Land?

    Comparison of an existing mobile home in a park, an existing manufactured home with owned land, and a manufactured home placed on private land.
    Separate an existing park-home purchase from an existing home with owned land and a private-land placement project before comparing costs and requirements.

    Whether you buy a mobile home in a park or with land depends on how much control you want and how the home and land are owned. In a park, you buy an existing home and rent the space it occupies. You may also have access to shared amenities and a community setting.

    Buying a manufactured home with owned land may give you more control over the property, subject to local rules and any other restrictions that apply.

    Financing may also differ. Some park homes are financed with home-only or personal-property loans, while some manufactured homes sold with owned land can use mortgage financing when the property and borrower meet the lender’s and loan program’s requirements.

    Before choosing, confirm the land or space arrangement and ask lenders which financing options they offer for that type of manufactured home.

    What Does a Mobile Home in a Park Cost?

    Purchase prices and space rents vary widely across San Diego mobile-home parks based on the specific home, community, location, and current park charges.

    For a park purchase, budget for the home price, space rent, separately billed utilities, insurance, maintenance, repairs, financing or closing costs, and any other recurring park charges that apply.

    Once you have a fully accepted offer on a specific home, ask the park manager for the current space rent, what it includes, and any other recurring charges. Use the SD Mobile Home Guide affordability calculator as an educational budgeting tool to compare those housing costs with your budget.

    Financing options can also depend on the home’s title or property status and the lender or loan program.

    What Does Land Need for a Mobile Home?

    If you are buying private land to place a manufactured home, confirm that local zoning allows the planned use and that the parcel can support the installation.

    Check access to water, electricity, and sewer or other approved wastewater service, and find out what utility connections the project requires.

    Ask the local building department what site, grading, soils, foundation, installation, and inspection requirements apply to that parcel.

    Foundation and installation requirements depend on the home, site, jurisdiction, and financing program. If the home will be permanently installed on owned land and treated as real property, recorded foundation documentation, including an HCD Form 433A when applicable, may be part of that process.

    These site-preparation and installation steps apply to a private-land project, not the normal purchase of an existing home already located in a San Diego mobile-home park.

    How Do Lot Rent and Ownership Affect Value?

    In a land-lease community, you own the mobile home but rent the space. That monthly payment affects your ongoing housing cost and is one factor buyers may consider when comparing a park home with a home sold with owned land.

    Once you have a fully accepted offer on a specific park home, get the current space rent, charges, and written rent terms directly from park management.

    The home and the underlying land are separate interests in a typical space-rent community, so buying the home does not mean you own the park space.

    Resident-owned, condominium, cooperative, or other ownership structures can work differently. Review the actual ownership and fee documents for the property rather than assuming every community uses the same arrangement.

    How Can You Finance a Park or Land Home?

    Manufactured-home financing depends on the home, the land or site arrangement, title and property status, the lender or loan program, and the borrower’s finances.

    For an existing home in a mobile-home park, ask lenders whether they finance used manufactured homes on rented or leased spaces and what home, park, or site requirements they have.

    For a manufactured home sold with owned land, ask about mortgage programs for manufactured housing and the property, foundation, appraisal, and title requirements that apply.

    Do not assume that owning the land automatically makes a particular FHA, VA, USDA, conventional, or other loan program available. Ask the lender to identify the programs it offers for the specific home and property.

    What Permits Does San Diego County Require?

    If you are placing a manufactured home on private land, the required permits and reviews depend on the parcel and the local jurisdiction.

    For property in unincorporated San Diego County, County Planning & Development Services is the local agency to ask about the project. Property inside an incorporated city may be handled by that city’s building or planning department.

    Ask the applicable agency which building, foundation, grading, utility, installation, and inspection requirements apply before committing to a private-land placement project.

    This permit discussion applies to installing a manufactured home on private land, not to the normal purchase of an existing home already located in a mobile-home park.

    Can the Parcel Support Utilities and Home Delivery?

    Before buying a parcel for a manufactured-home placement project, confirm that it can support the home and provide access for delivery and installation.

    Check whether water, electricity, and sewage connections are available, and ask the relevant utility providers or local agencies what installation requires. If public connections are not feasible, confirm what private systems are allowed and suitable for the site.

    Review zoning, site conditions, and access requirements with the appropriate local agencies and professionals.

    Also check that the site’s dimensions and layout leave enough room for delivery vehicles and installation equipment to reach the placement area.

    Which Option Fits Your Budget and Lifestyle?

    Neither a park home nor a home with owned land is automatically the less expensive choice. Compare the actual purchase price and the ongoing costs for the specific property.

    A park purchase adds space rent and any recurring park charges. A home with owned land has a different cost structure, while a private-land placement project can also involve delivery, site preparation, permits, foundation work, and utility connections.

    Financing can differ too, so compare the actual loan terms available for the home and land arrangement you are considering.

    Also consider how much you value community amenities and shared rules compared with greater control over owned land.

    Conclusion

    For a San Diego park purchase, you are typically buying an existing home already located in the community and separately budgeting for space rent and other recurring costs. Once you have a fully accepted offer, get the current rent, written rules, utility information, and residency-approval requirements from the park manager before completing the purchase.

    If you are buying a manufactured home with owned land, review the home and property together. If you are buying private land to place a manufactured home, also account for zoning, delivery, site preparation, permits, utilities, and installation. Compare the full costs, financing options, and level of control each arrangement offers before deciding.

  • How Manufactured Home Financing Differs From Traditional Home Financing in California

    How Manufactured Home Financing Differs From Traditional Home Financing in California

    How Manufactured Home Financing Differs From Traditional Home Financing in California

    In California, manufactured-home financing can differ from mortgage financing for a site-built house because the home may be financed separately from the land or as part of real property with owned land. For an existing home in a mobile-home park, the buyer is typically financing a home that is already located in the community while separately budgeting for space rent and other recurring park costs. For a manufactured home sold with owned land, mortgage financing may be available when the property meets the lender’s and loan program’s requirements.

    The available options depend on the home, land ownership or site arrangement, title and property status, age and condition, applicable HUD construction standards, the loan program, the lender, and the borrower’s finances. Some government-backed programs also allow financing for manufactured homes on leased lots. SD Mobile Home Guide is not a lender or underwriter. Before comparing loan payments, you can use the SD Mobile Home Guide affordability calculator as an educational budgeting tool to estimate how the home payment, space rent when applicable, and other housing costs may fit your budget.

    How Are Manufactured Home Loans Different?

    A traditional real-estate mortgage is secured by real property. Manufactured-home financing can work differently because some transactions finance the home itself without the land, while others finance the home and owned land together.

    A loan secured primarily by the manufactured home rather than the land is often described as personal-property or chattel financing. A mortgage product for a manufactured home generally has separate property, foundation, title, appraisal, and program requirements.

    Requirements are not the same across every lender or loan program. Ask potential lenders whether they finance the specific type of manufactured home and land arrangement you are considering and which property requirements apply.

    How Does Land Ownership Shape Your Loan Options?

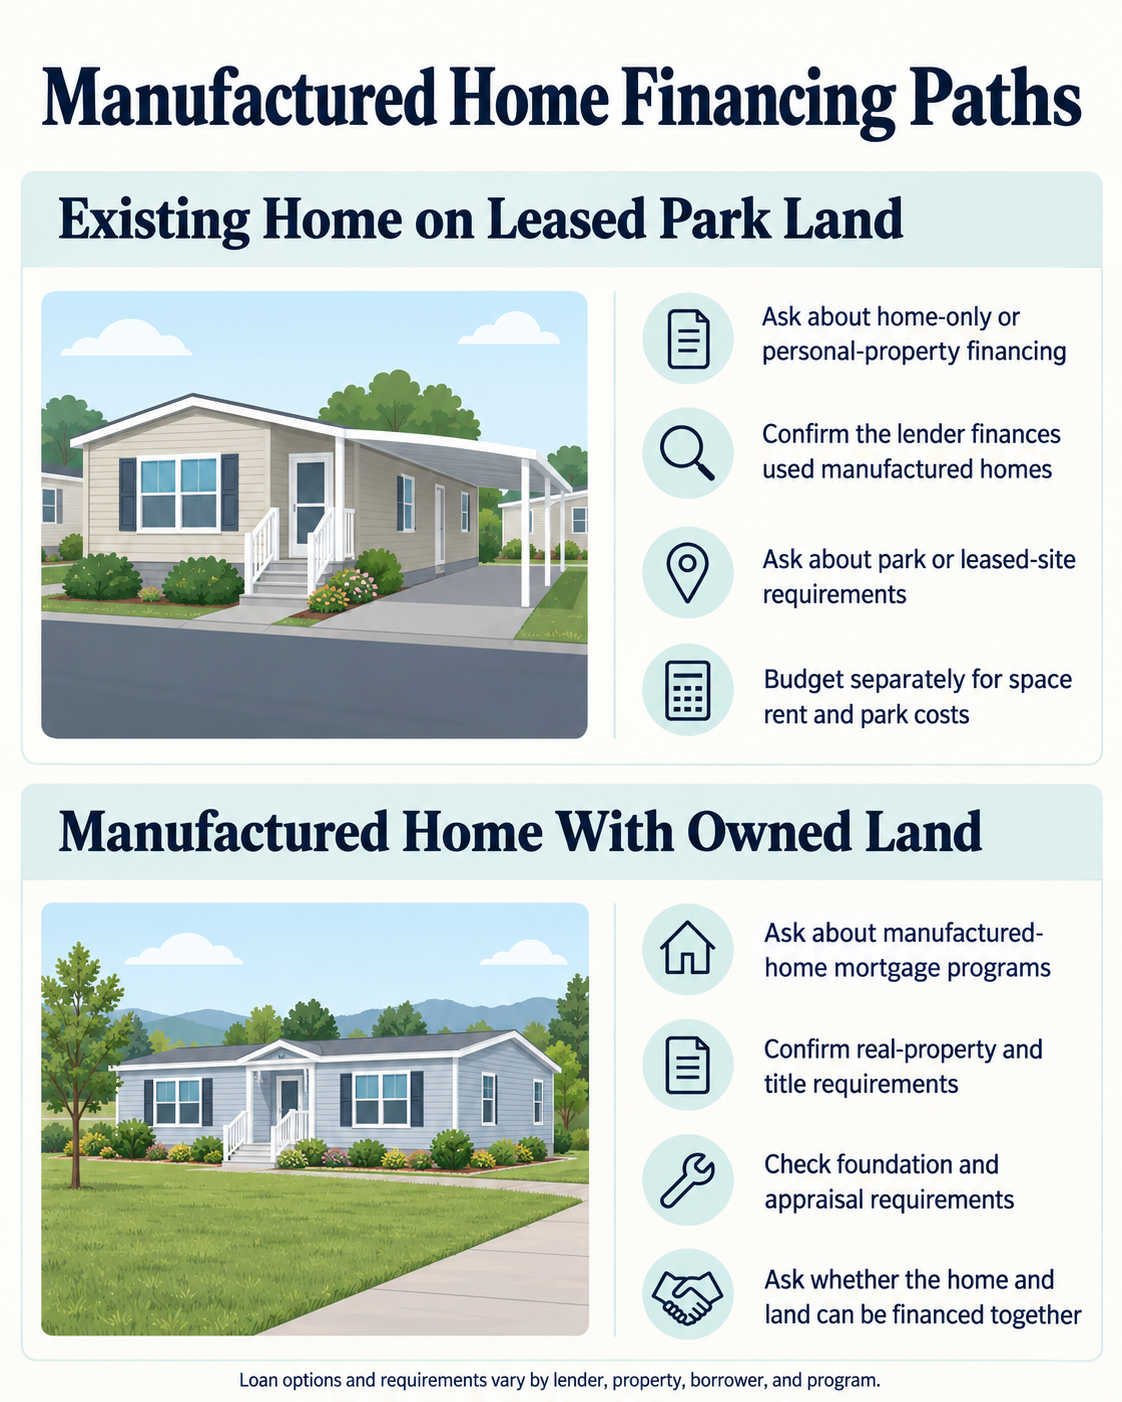
    Comparison of financing questions for a manufactured home on leased park land versus a home with owned land.
    Match the financing questions to whether the manufactured home is on leased park land or sold with owned land.

    Land ownership is one of the main differences between manufactured-home financing and financing for a conventional site-built home.

    If you are buying an existing home in a San Diego mobile-home park, the home is already located on a rented space. Ask lenders whether they finance used manufactured homes on leased land and what park, lease, or site requirements they have. Separately, after you have a fully accepted offer, get the current space rent, written park rules, utility information, and residency-approval requirements directly from park management.

    If you are buying a manufactured home with owned land, ask lenders about mortgage programs that finance the home and land together and what real-property, foundation, appraisal, and title requirements apply.

    Land ownership is not the only path to manufactured-home financing. For example, FHA’s Title I Manufactured Home Loan Program can finance a manufactured-home unit on a leased lot when the program’s requirements are met. The availability of any particular program still depends on the lender, property, borrower, and current program rules.

    When Can Mortgage Financing Be an Option?

    Mortgage financing can be an option when the manufactured home and property meet the requirements of the specific mortgage program and lender.

    For example, Fannie Mae’s manufactured-housing guidelines require the home to be attached to a permanent foundation system and the home and land to be legally classified as real property. Other mortgage and government-backed programs have their own requirements.

    Manufactured homes built under the federal HUD Code carry certification labels and have a data plate with identifying and construction information. The HUD Code took effect for manufactured homes produced on or after June 15, 1976. A lender or loan program may require evidence that the home meets applicable manufactured-housing standards, but the exact documentation varies by program.

    Ask the lender to identify the property, foundation, appraisal, occupancy, title, and borrower requirements for the specific program before relying on that financing option.

    What If the Manufactured Home Is Personal Property?

    If the manufactured home remains titled as personal property, financing may involve a home-only or personal-property loan rather than a real-estate mortgage. This is a common financing category to ask about when the home is in a mobile-home park and the buyer rents the space.

    The home serves as collateral for this type of financing rather than the underlying land. Interest rates, terms, down-payment requirements, fees, and underwriting standards vary by lender and product, so compare the actual loan disclosures rather than assuming the terms will match a mortgage.

    For a California HCD-titled home, confirm that the seller or mobile home sales agent has the current title and registration ready for transfer. The originals should remain secure and move through the transaction or escrow process as appropriate rather than being casually handed to the buyer.

    Which Financing Options Should You Ask About?

    The most useful starting point is to match the financing question to the property you are actually buying.

    For an existing home in a mobile-home park, ask lenders specifically about financing for a used manufactured home on leased land and what they require for the home, park, and site arrangement.

    For a manufactured home sold with owned land, ask about mortgage products for manufactured housing and the program’s real-property, foundation, appraisal, and title requirements.

    If you are buying a manufactured home and private land together, ask whether the lender can finance both in one transaction and what site or installation documentation applies. Those installation and site-work questions generally relate to a private-land placement project, not the normal purchase of an existing home already located in a San Diego mobile-home park.

    SD Mobile Home Guide is not a lender or underwriter. A lender must determine what financing, if any, is available for the specific borrower and property.

    What Do Manufactured Home Loans Cost in California?

    The cost of manufactured-home financing depends on the loan type, interest rate, annual percentage rate, term, down payment, and applicable fees.

    Depending on the product and transaction, costs can include origination, appraisal, title, recording, insurance, or other charges. Not every fee applies to every loan.

    Compare the annual percentage rate, monthly payment, cash needed at closing, loan term, fees, and total repayment information shown by each lender. A lower monthly payment does not necessarily mean a lower total borrowing cost.

    If the home is in a park, include the current space rent, separately billed utilities, insurance, maintenance, and other recurring park or housing costs when deciding whether the overall purchase fits your budget.

    What Should You Prepare Before Applying for a Loan?

    Ask each lender which documents it requires before you apply, because the list can vary by loan product and transaction.

    A lender may request information about income, assets, debts, credit, and the purchase agreement. For the home, it may also request identifying information, age, title or registration information, appraisal or inspection information, insurance details, and evidence related to HUD construction standards when applicable.

    If you are buying an existing park home, confirm that the seller or mobile home sales agent has the title and registration ready for transfer. After a fully accepted offer, get the current space rent, rules, utility information, and residency-approval requirements from the park manager, and ask the lender which park or rental documents it needs.

    If you are buying a manufactured home for private land rather than an existing park home, the lender may also ask for land, foundation, installation, site, or utility documentation that applies to that project.

    Conclusion

    Manufactured-home financing in California depends on more than the buyer’s finances. The home’s title and property status, whether the land is owned or leased, the type and age of the home, and the lender or loan program can all affect which financing paths are available.

    For a San Diego park purchase, focus on lenders that finance existing manufactured homes on leased spaces, confirm the seller or mobile home sales agent has the title and registration ready for transfer, and include the current space rent and other recurring costs in your budget. For a home with owned land, ask about manufactured-home mortgage programs and their property requirements. Compare the actual terms and disclosures from lenders before choosing a financing option.